
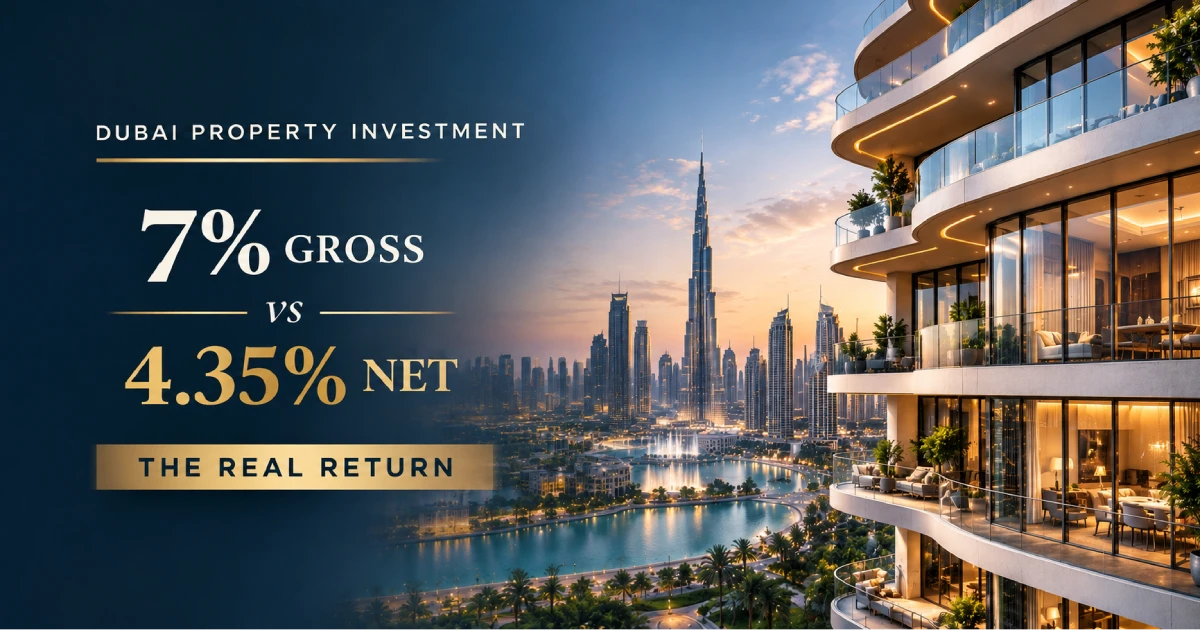
How a 7% rental yield on a brochure turns into something much smaller once you count every cost, line by line
Prime Bullions Properties publishes plain-English guides for people about to invest in Dubai real estate.
Thinking about a purchase? Sit down with an advisor, ask every question you have, and leave with a clearer picture of the numbers. No obligation to buy.
Hi, it’s the Prime Bullions team. Every week we write about what we see on the ground in Dubai real estate, for people who are about to put real money into a property.
The yield in the brochure and the yield in your bank account are rarely the same number. If you are still working out what your budget can buy, start with our guide to what AED 650,000 to AED 1 million can buy in Dubai. Today we cover the part that never makes it onto the listing: where the return actually goes.
By the end you will be able to take any listing, strip it down to a net yield, and ask better questions before you make an offer. There is also a simple three-scenario table you can copy for your own numbers.
Picture an investor about to buy his first Dubai property. Versions of this conversation land in our inbox every month, so we will tell it as a composite.
He has found a one-bedroom apartment in a well-known community. The price is AED 1 million. The listing says the rental yield is 7%. It looks great. He sends it over with one question: is this a good deal?
We asked him one back. Where does the 7% come from?
He did not know. It came from the listing, which was the only place he had seen it. Nobody had told him what was inside the number, or what was left out.
Nobody had shown him what the number leaves out.
The short version:
- Gross yield is annual rent divided by price. It leaves out almost every cost of owning the property.
- In our illustrative example, a 7% gross yield turns into roughly 4.35% net once the costs are counted.
- The service charge alone can move the net yield by half a point between two otherwise identical buildings.
- Check every estimate against a real quote before you make an offer.
The number everyone quotes
Pull one string and the whole return unravels
Between the rent you charge and the money that reaches your account sits a stack of costs. Most owners we talk to can name two or three of them. Very few can name all of them.
The point is not to scare anyone off. A property can still be a good investment after every cost is counted. But you want to find that out before you buy, not after the first service charge invoice lands.
The costs that sit between gross and net
- Buying costs. Registration, agency fees and, if you finance the purchase, mortgage arrangement fees. Amounts and rules change, so confirm current figures with the Dubai Land Department and your broker before you run any numbers. These raise what you actually paid, so the same rent becomes a smaller percentage of a bigger base.
- Service charges. You pay these every year whether the unit is rented or empty. They differ from building to building, depending on facilities and how the community is run. Ask for the latest charge per square foot, in writing.
- Vacancy. The gap between listing the unit and signing a lease, and the gap between one tenant leaving and the next arriving. Even a few weeks a year takes a visible bite.
- Furnishing and refresh. If you rent furnished, furniture wears out and walls need repainting between tenants. It is easy to forget because it does not arrive as a monthly bill.
- Maintenance and repairs. Plumbing, appliances and air conditioning. In this climate, cooling alone can become a real line item.
- Property management fees. If you use a manager, expect a share of the annual rent or a set fee. Owners who live overseas almost always need one.
- Leasing and renewal fees. Finding a tenant, and renewing one, can both carry a cost.
- Insurance. A landlord needs the right cover in place. We walk through the options in our Dubai property insurance guide for homeowners and landlords.
- Financing costs. If you have a mortgage, the interest comes out of the same income, so compare it against your net return, not your gross one.
None of these are unusual. All of them are missing from the brochure.
The same property, with the costs added in
Here is a simple example using round numbers. These figures are illustrative only. Swap in the real ones for any property you are looking at.
| Line | AED per year |
|---|---|
| Rent received (gross) | 70,000 |
| Service charge | -12,000 |
| Vacancy (about three weeks) | -4,000 |
| Management (5% of rent) | -3,500 |
| Maintenance and repairs | -2,500 |
| Furnishing refresh | -2,000 |
| Insurance | -1,500 |
| Leasing and renewal | -1,000 |
| Net income | 43,500 |
| Gross yield on AED 1,000,000 | 7.00% |
| Net yield on AED 1,000,000 | 4.35% |
Illustrative figures only. Your building, tenant and management terms will differ.
The 7% became 4.35%. About 38 percent of the rent went to costs. And this table does not include what you paid to buy the property or any mortgage interest, so the real picture for a financed purchase can be tighter still.
Same price, same headline yield, different outcome
Now take two apartments, both priced at AED 1 million and both advertised at 7%. In the first building the service charge is AED 12,000 a year. In the second it is AED 7,000. Everything else stays the same.
The first one nets 4.35%. The second nets 4.85%. That is half a percentage point on a million dirham purchase. If the charge stayed flat, the gap would be AED 50,000 over ten years, and it comes from a single line you can check before you make an offer.
This is also why we suggest comparing at least three units the same way. Browse our current apartments and studios, pick a few, and run the same exercise on each.
Stress-test your own numbers
You do not need special software for this. A simple three-scenario check does the job, and it takes about twenty minutes with a spreadsheet.
Net yield = (annual rent - annual costs) / purchase price
Run it three times, changing only the vacancy: two weeks, six weeks and ten weeks a year.
Here is what that looks like for the example above, with every other cost held steady:
| Scenario | Vacancy cost | Net income | Net yield |
|---|---|---|---|
| Best case (2 weeks empty) | 2,700 | 44,800 | 4.48% |
| Typical (6 weeks empty) | 8,100 | 39,400 | 3.94% |
| Cautious (10 weeks empty) | 13,500 | 34,000 | 3.40% |
Illustrative figures in AED per year, using the example property above.
Same building, same rent, and the net yield swings by more than a full percentage point depending on how long the unit sits empty. Here is how to build your own version:
- Start with rent you can prove. Use recent rents for similar units in the same building, not the figure on the listing.
- Fill in every cost line. Use the table earlier in this article as your template and put a real quote next to each line.
- Run the three vacancy scenarios. Two, six and ten weeks cover most realistic outcomes.
- Find the line that moves the result most. It is usually the service charge or the vacancy gap. That is where to push for better information.
- Swap estimates for invoices. After the first year, replace every guess with what you actually paid.
Pro-tip: Do the sums once with hopeful numbers and once with cautious ones. If the deal only works in the first version, you have learned something important before spending a dirham.
Where first-time and overseas investors get caught
We see the same few things again and again:
- Assuming the unit is rented all year. Build in vacancy from the start, even if the first tenant arrives quickly.
- Forgetting the months before rent begins. If you buy off-plan, rent does not start until handover, but the payment plan keeps running.
- Underestimating distance. Managing from abroad means someone else deals with the tenant, the repair and the renewal. That someone has a fee.
- Ignoring currency. If your income is in another currency, check how exchange rates affect what you send and what you earn.
- Judging a building by its photos. The service charge statement tells you more than the lobby does.
Questions to ask before you make an offer
Send these to any broker, including us:
- What is the current annual service charge, and has it changed in the last two years?
- How long did this unit take to rent last time, and at what rent?
- What is the realistic rent range, and what is it based on?
- Who handles maintenance, and who pays for it?
- What does property management cost, and what does it include?
- Are there any planned works or special charges in the building?
- What are all the one-off costs at purchase, listed out line by line?
If the answer is a range, ask what assumptions sit behind it.
Thanks for reading the Prime Bullions blog. If you have a listing you would like a second opinion on, send it over and we will run the numbers with you.
The takeaway
A high gross yield is a starting point, not a verdict. It tells you the property can earn. It does not tell you what you keep.
In our experience, the investors who do well are not the ones who found the biggest number. They are the ones who checked the costs, asked about the building, and bought with a realistic net figure in mind.
Want to run this yourself? Here is the checklist:
Collect these
- The listing and the rent it claims
- The latest service charge figure, in writing
- Recent rents for similar units in the same building
- Quotes for management and maintenance
Create these
- A simple sheet with gross rent and every cost line
- Three vacancy scenarios: short, typical and long
Work out these
- A net yield under each vacancy scenario
- The one assumption that moves the result most
Then, as you go
- Replace every estimate with a real quote or invoice
- Review the numbers again after the first year of ownership
One last thing. Take your sheet to every viewing and fill in the blanks as you go. The gaps show you exactly what to ask next.
What else you should know:
- Free private consultation: Talk through your budget and goals with an advisor. Book a time here.
- Browse current listings: Compare apartments, studios and more across Dubai. See all properties.
- Keep reading: Thinking about a second purchase? Read Residential or Commercial Property in Dubai: Where Should Your Next Investment Go?